Put Your Home Equity to Work.
Explore a line of credit or home equity loan for renovations, debt payoff or your next plan, alongside your existing mortgage.
- Compare a HELOC with a home equity loan
- Discuss options alongside your existing mortgage
- Start with your property and goals
What Will You Use the Funds For?
Explore an Equity Scenario.
Adjust the property value, existing balance and terms to compare a planning scenario.
- Current Home Equity
- $210,000
- Amount Modeled
- $60,000
- Interest-Only Example
- $425/mo
- Amortizing Payment Example
- $591/mo
Planning estimate, not a loan offer or eligibility result. Calculator Assumptions
Three Steps to a Clear Answer.
Share Your Equity Goals
Tell us about your home and existing mortgage.
Compare the Structures
Discuss a revolving line versus a lump-sum loan, costs and repayment.
Choose Your Next Step
Move forward after a personal review of your options.
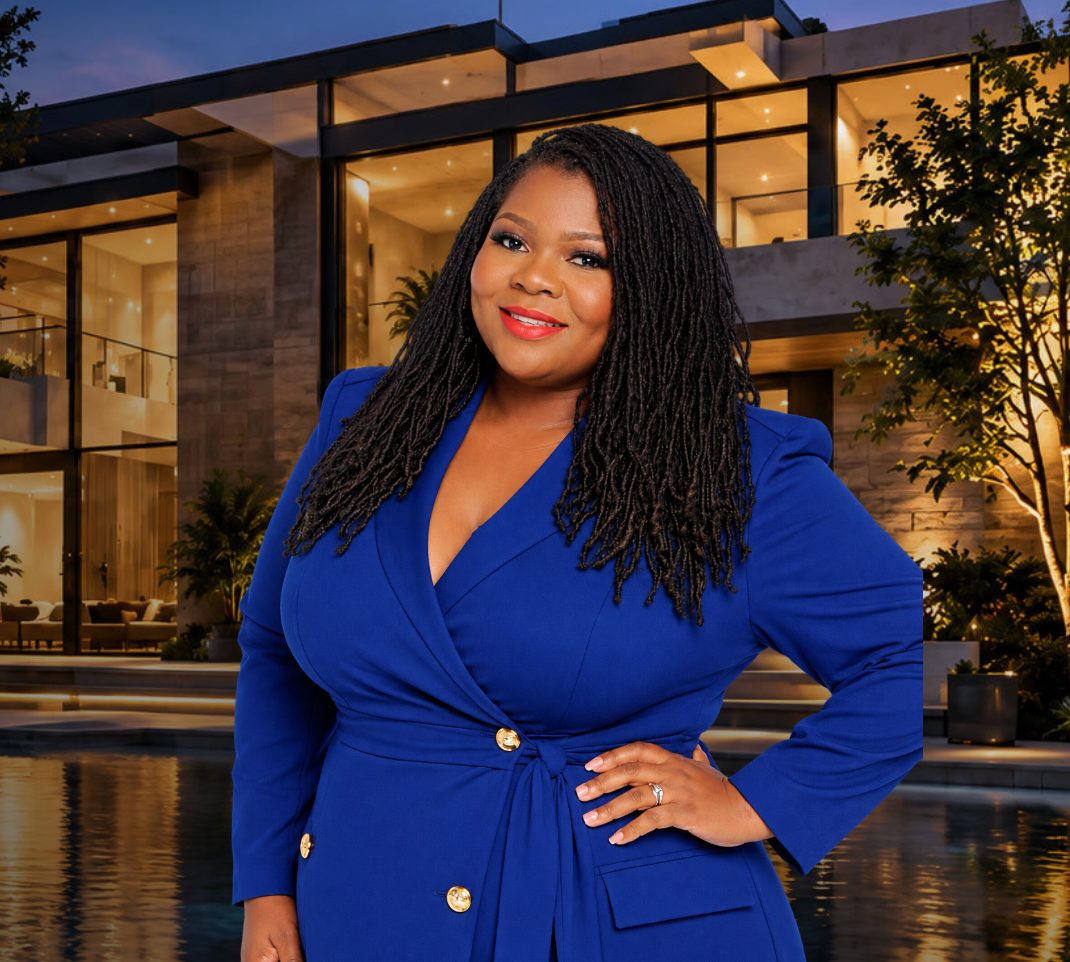
Work Directly with Mika Akindoju.
Connect with Mika to discuss your financing goals and the next steps for your purchase or home-equity inquiry.
Keep Mika in Your Phone.
Save Mika’s contact so you can reach your loan officer when a question comes up.
Common Questions.
What Is the Difference Between a HELOC and a Home Equity Loan?
A HELOC is a revolving credit line. A home equity loan generally provides a lump sum. Compare rates, fees and repayment terms with your loan officer.
Would This Replace My First Mortgage?
Home equity financing may sit alongside an existing mortgage. The appropriate structure depends on the product and property.
How Much Can I Borrow?
Available credit depends on property value, existing liens, lender guidelines and state rules. The calculator illustrates a scenario; it does not determine eligibility.