Investor Financing That Qualifies the Property, Not Just Your W-2.
Explore DSCR, alternative income documentation and investment-property financing with your loan officer.
- Discuss rental-income-based DSCR financing
- Explore alternative documentation for self-employed borrowers
- Review your property and ownership plans
What Type of Property?
See How Rent Compares with the Payment.
Explore the numbers using your own property assumptions.
- Monthly Payment with Tax, Insurance & HOA
- $2,396
- Monthly Rent
- $2,650
- Rent Minus Entered Payment
- $254
- Loan Amount
- $243,750
Planning estimate, not a loan offer or eligibility result. Calculator Assumptions
Three Steps to a Clear Answer.
Share the Deal
Property type, price and how you would like to document income.
Discuss a Scenario
Review potential structures and the information lenders need.
Plan the Application
Your loan officer helps coordinate the next step.
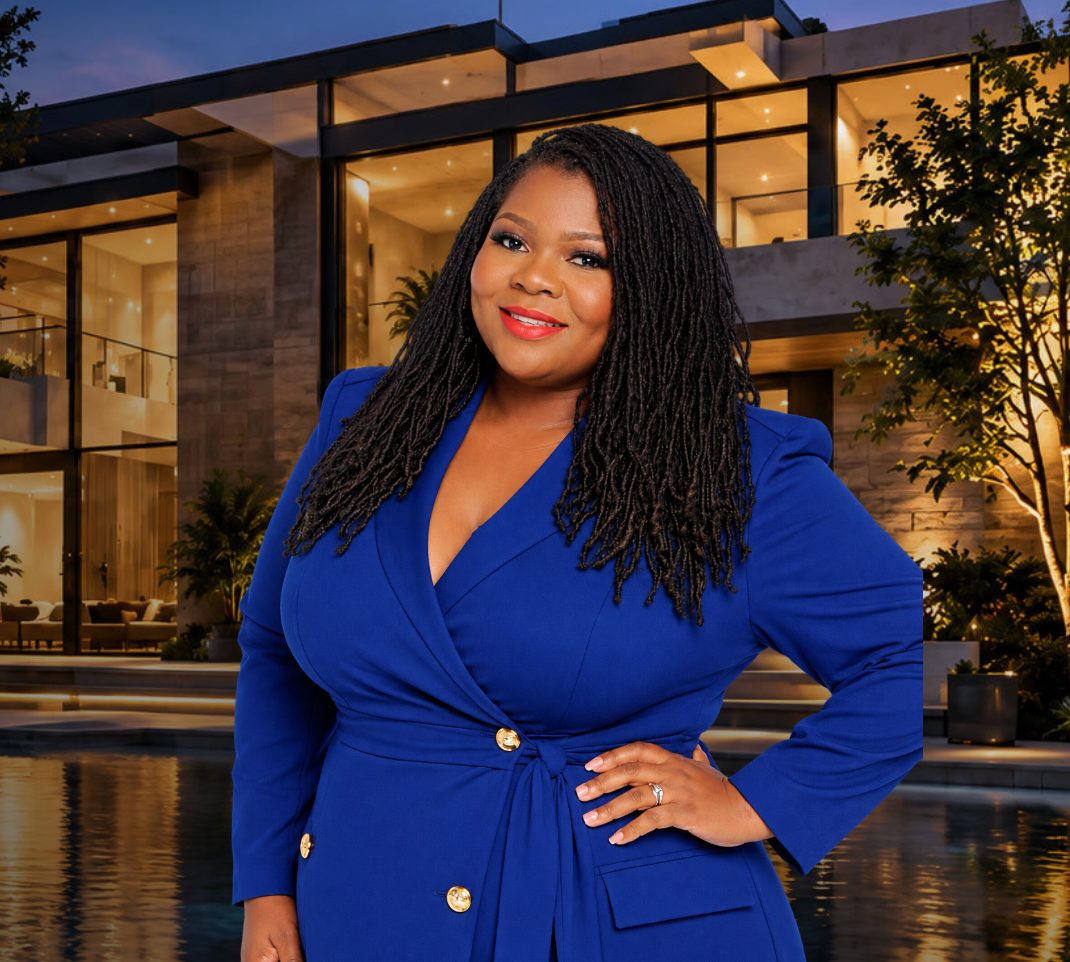
Work Directly with Mika Akindoju.
Connect with Mika to discuss your financing goals and the next steps for your purchase or home-equity inquiry.
Keep Mika in Your Phone.
Save Mika’s contact so you can reach your loan officer when a question comes up.
Common Questions.
What Is a DSCR Loan?
DSCR financing considers the property’s rental income relative to its debt service. Guidelines and additional borrower requirements vary by lender.
Can I Close in an LLC?
Discuss your ownership structure with your loan officer. Entity requirements depend on the lender and product.
What About Short-Term Rentals?
Share the property and rental-income information so your loan officer can review potential options.